
Your Health Insurance Renewal Just Went Up 22%. Now What?
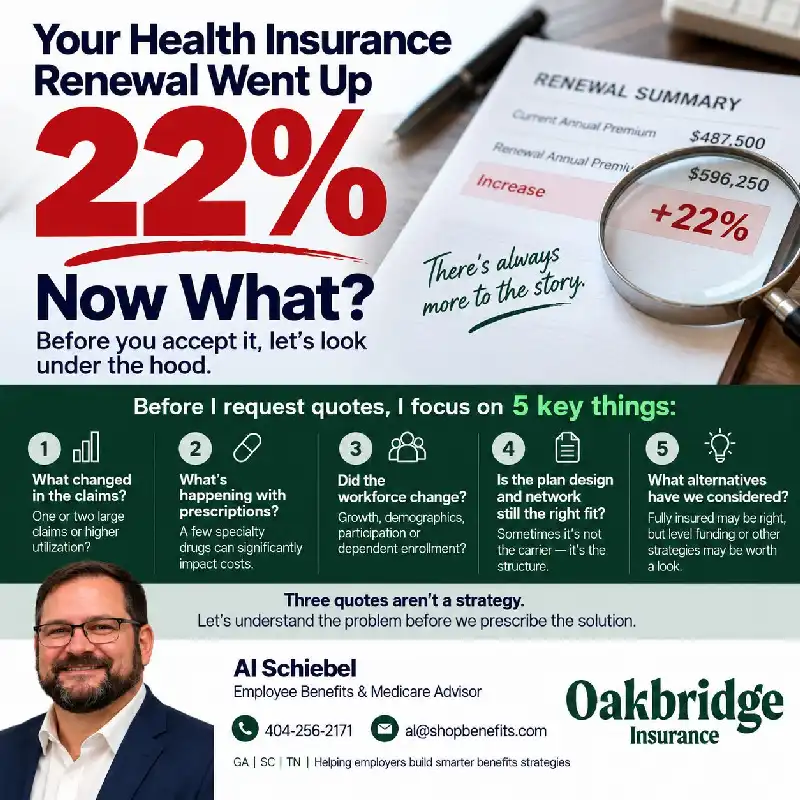
When a health insurance renewal comes back with a steep double-digit increase like 22%, the natural knee-jerk reaction for most business leaders is simple: “Let’s get some quotes.” While shopping the market can sometimes be necessary, simply gathering three quotes isn’t a strategy. A 22% increase tells you what happened to your premium, but it does not tell you what is causing the rate hike[cite: 1]. If you change nothing except the insurance carrier, you haven’t actually addressed the root drivers behind your cost increases[cite: 1].
Before you run out of options or accept an unsustainable rate hike, it is critical to look under the hood[cite: 1]. If your renewal is coming up in the next 90 to 120 days, now is the time to evaluate the foundational health of your benefits program[cite: 1].
5 Diagnostic Questions to Ask Before Shopping Carriers
Before requesting quotes from competing carriers, evaluate these five critical operational areas to uncover the real story behind your numbers[cite: 1]:
- 1. What changed in the claims? Determine whether your cost increase was driven by one or two isolated high-dollar claims or if utilization is rising across your entire employee group[cite: 1].
- 2. What’s happening with prescriptions? Specialty medications can have an outsized impact on spend, particularly for small to mid-sized employers where a handful of prescriptions can dramatically shift overall costs[cite: 1].
- 3. Did the workforce change? Shift changes in workforce growth, age demographics, overall plan participation, and dependent enrollment can fundamental alter the economics of your healthcare plan[cite: 1].
- 4. Is the current plan design and network still the right fit? Cost relief often lies in how your plan is structured or how employees access care rather than in switching carriers altogether[cite: 1].
- 5. What funding alternatives have we actually considered? While remaining fully insured may still be the right fit, exploring level funding or other modern funding strategies may unlock significant financial control[cite: 1].
Diagnosing the Problem Before Prescribing the Solution
Shopping the market without analyzing your underlying claim drivers simply moves an unchecked problem from one insurance company to another[cite: 1]. To build a resilient employee benefits strategy, leadership must first identify what problem needs to be solved before selecting a replacement carrier[cite: 1].
“If we change nothing except the insurance carrier, have we actually addressed what caused the increase?”[cite: 1]
Let’s Look Beyond the Spreadsheet
If you’re ready to stop guessing and start managing your benefits proactively, we can help you uncover the real story behind your numbers[cite: 1]. If your health plan renewal is within the next 90–120 days, let’s have a 15-minute conversation to look under the hood[cite: 1].
Connect with Al Schiebel today:
- Email: al@shopbenefits.com[cite: 1]
- Phone: 404-256-2171[cite: 1]
ShopBenefits is an Oakbridge Insurance Agency partner serving employers in GA, SC, and TN.[cite: 1]